


The Right Kind of Deposits: Why Profitability Matters More Than Volume
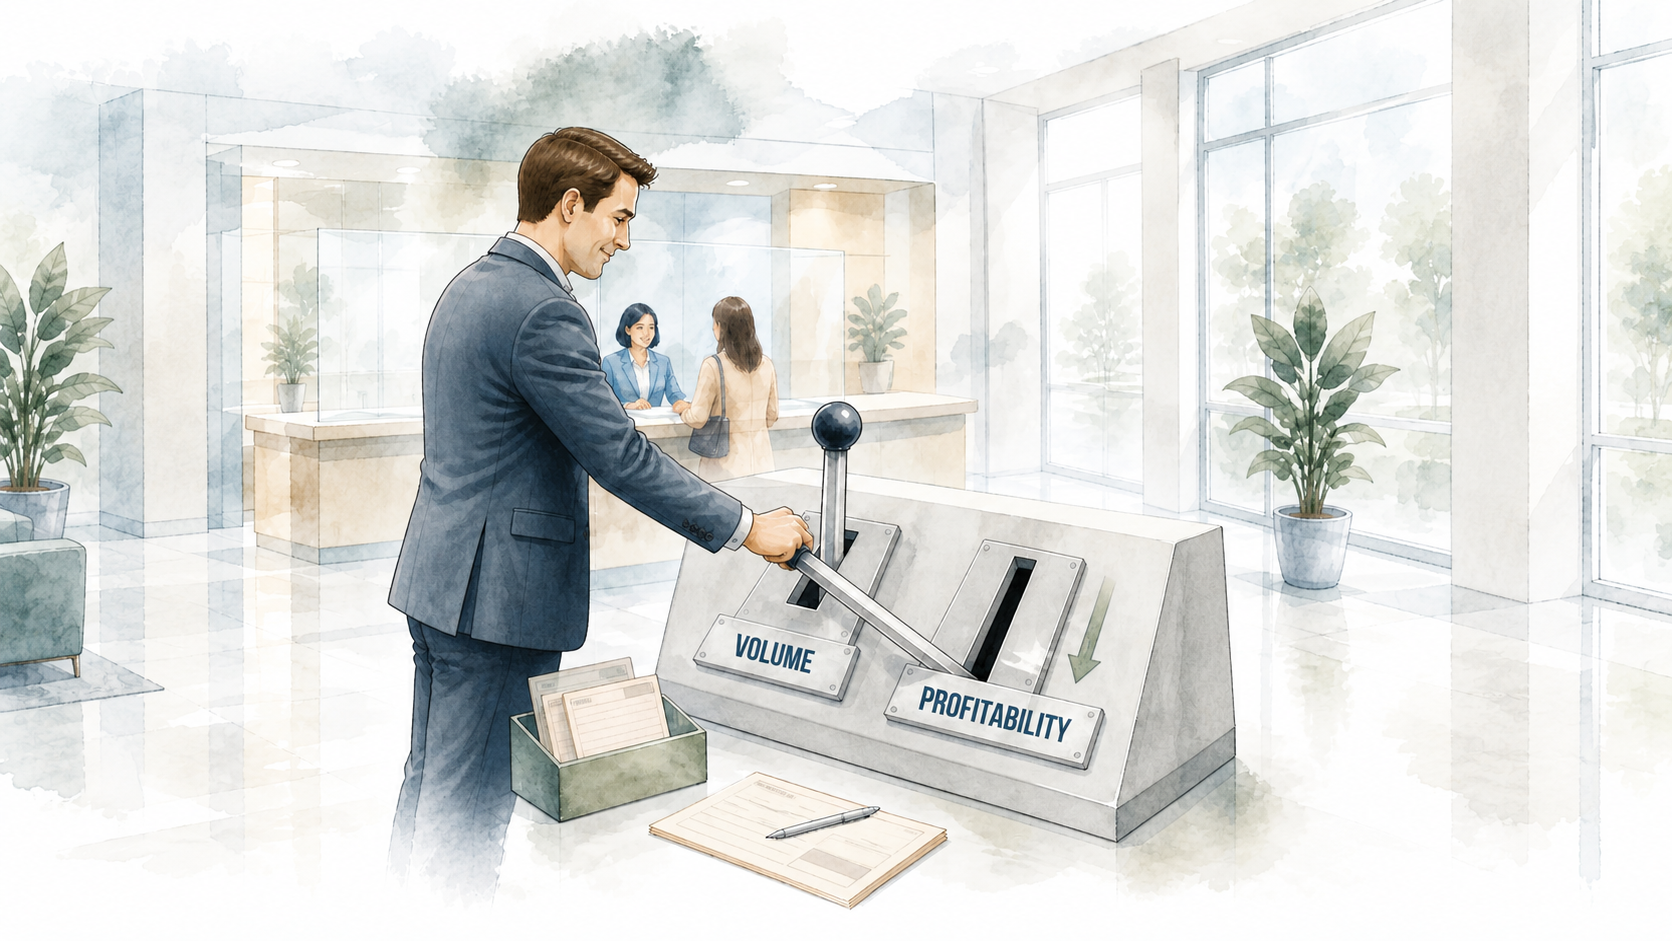
Deposit growth looks good on the balance sheet, until you start to peel back the layers of what built the growth.
Think about the cost of acquiring and funding each new account, the time spent on fraud reviews, and how many of those new accounts are still active a few months later.
Include added fraud risks, cost of technology, and additional staffing needs, and the underlying price behind the growth becomes, in some cases, unsustainable.
Liquidity, not just volume. Growth that doesn’t improve liquidity is a short-term Band-Aid. Banks need funded, transacting accounts.
Lowering cost of funds. High-cost CDs, rate chasers, and one-time promotions move the needle short term. Long-term profitability requires deposits that align with the bank’s lending strategy and margin goals.
Improving deposit mix. Getting the right customer matters as much as getting more customers. Diversifying by industry, segment, and product type builds a healthier funding base and better cross-sell potential.
Legacy workflows, siloed tech, rising costs, and fear of fraud make it hard to scale deposit growth without adding headcount.
Staff work around the system. Key steps move to email and spreadsheets. The digital solution ends up creating more work than it was meant to remove.
Digital account opening tools fall into this pattern when they focus on forms instead of the full customer journey: risk, compliance, operations, funding, and beyond. When that happens, deposit growth stops being a profitability lever.
When banks build for this, metrics that start to matter more than accounts opened. These include:
These are the numbers that strengthen the balance sheet.
Improving deposit profitability will take more than a just a new form.
Banks need infrastructure that embeds compliance, fraud controls, and customer intelligence directly into the onboarding and funding flow. That includes faster decisioning, fewer handoffs between systems and departments, and less clean-up after the fact. On top of that, risk and fraud needs to work together under the same system, as well as full visibility into which relationships are important.
Linker builds that infrastructure for community banks. Partner banks working with us see the difference in real-time. Fewer accounts fall out of the process before funding and fewer require manual reviews. Expansion into new markets doesn’t result in an expansion of headcount.
Banks can’t afford to chase deposits at any cost, especially in rising interest rate environments. What makes the biggest difference? Deposits that improve liquidity, lower the blended cost of funds, strengthen deposit mix, and support profitable lending and long-term relationships.
This requires a shift from acquisition as a stand-alone to looking at the full customer journey. Prioritize who you attract, how you onboard them, how you fund them, how well you retain and expand that relationship over time.


